
Why a $144,000 UTV Rental Fleet Deducts in Full but May Not Offset Wages
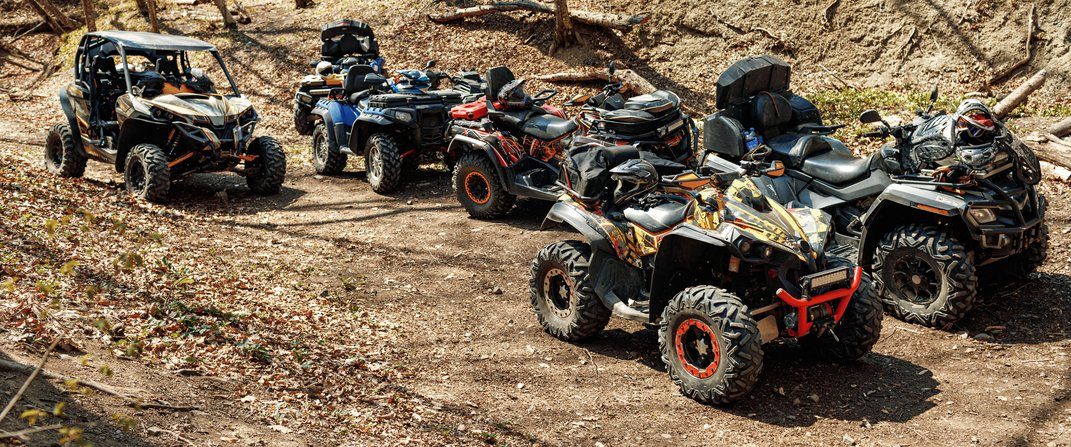
Powersports units are not passenger automobiles, so a rental fleet deducts its full cost in year one with no dollar cap. Whether the loss reaches your other income depends on your hours, and with paid guides the 500-hour test is usually the one that fits.
"I rent six UTVs out of a shop near the trailheads and pay three guides. If I buy the fleet this year, can the loss come off my spouse's salary?"
The question this post answersNo dollar cap applies to UTVs, ATVs, dirt bikes or snowmobiles. None of them is a passenger automobile, unlike a Turo car, and a shop renting to the public all season gets 100% bonus depreciation on the full cost of its UTVs in the year they go into service.
Whether a year-one loss reduces tax on your other income is a separate question. It turns on material participation, meaning how many hours you work in the shop compared with the guides and counter staff you pay.
1 A UTV is not a passenger automobile
The luxury auto cap in section 280F only reaches a "passenger automobile." Section 280F(d)(5) defines that as a 4-wheeled vehicle "manufactured primarily for use on public streets, roads, and highways" and "rated at 6,000 pounds unloaded gross vehicle weight or less." UTVs and ATVs are built and sold for off-road use. If your state lets you plate one for the road, the plate does not change what it was manufactured primarily for.
Snowmobiles and dirt bikes fail sooner, because neither has four wheels. So the $20,300 first-year limit for 2026 cars in Rev. Proc. 2026-15 never enters the math, whatever a UTV costs.
2 It is still listed property
Section 280F also defines listed property to include "any other property used as a means of transportation" and property "of a type generally used for purposes of entertainment, recreation, or amusement." The regulation lists trucks, buses, boats, motorcycles "and any other vehicles for transporting persons or goods." A UTV fits the first category, and arguably the second.
Listed property carries two extra rules:
- The 50% test. If a UTV is not used more than 50% in a qualified business use in a year, depreciation drops to the alternative system, straight-line with no bonus. Qualified use excludes leasing to a 5% owner or a related person, and letting either of them use it as compensation for work.
- Section 274(d)(3) records. No deduction is allowed unless you can prove the cost, the business and total use, the date, and the purpose. For vehicles the regulation measures use in miles.
3 A rental shop steps outside section 280F
Section 280F(c)(1) says the section "shall not apply to any listed property leased or held for leasing by any person regularly engaged in the business of leasing such property." The regulation turns off both the dollar limits and the 50% test for that person, and it calls you regularly engaged when rental contracts are "entered into with some frequency over a continuous period of time."
A shop writing hundreds of rental agreements a season on six UTVs, with posted hours and a booking page, meets that description.
A guided ride where the guide sets the route and controls the outing can look more like a service contract than a lease under section 7701(e), and that would weaken the leasing exception. The 50% test is the backstop, and a UTV that only goes out to paying customers clears it, provided you log every non-business ride by you, your family or your staff.
Bonus itself is settled. P.L. 119-21 set section 168(k) at 100% and repealed the phase-down in section 168(k)(6), for property acquired after January 19, 2025. A UTV bought under a written binding contract signed on or before that date and placed in service in 2026 falls back to the old 20% rate. Used UTVs qualify if you never used them before and did not buy them from a related party.
4 Seven-year property, and why the class matters less this year
Rev. Proc. 87-56 has no asset class for UTVs, so you classify by activity. Class 57.0, Distributive Trades and Services, covers retail and "personal and professional services" and is 5-year property. Class 79.0, Recreation, covers "assets used in the provision of entertainment services on payment of a fee or admission charge" and is 7-year property with a 10-year class life.
We use 79.0. The Standard Industrial Classification manual lists motorcycle, moped, go-cart and golf cart rental under amusement and recreation services, code 7999. A 2001 IRS field service advice memo (FSA 200203009) relied on that code to put casino gaming assets in 79.0 rather than 57.0. The memo is not precedent. Treas. Reg. §1.167(a)-11(e)(3)(iii) also says a lessor's property is classed as if the lessee owned it, and a tourist's use fits no class, which points to 57.0 or to property with no class life (7-year, with a 12-year alternative period). Every reading gives 5- or 7-year property and the same 100% bonus.
The class matters if you elect out of bonus, on a state return that does not follow federal bonus, and in the section 179 lessor test.
Section 179 is the backup. For 2026, Rev. Proc. 2025-32 sets the limit at $2,560,000, reduced once you place more than $4,090,000 of property in service. It is also capped at your taxable income from active businesses, so in a loss year bonus does the work. A noncorporate lessor can use section 179 only if the lease term is under half the class life and, for the first 12 months, its section 162 expenses on the property, other than rents and reimbursed amounts, exceed 15% of the rental income. A four-hour rental passes the first part. Fuel, repairs and insurance count toward the second, guide wages are doubtful, and a busy shop should still pass.
5 Hourly rentals fall under the business rules
Under the passive loss regulations, renting out property is not a "rental activity" when the average period of customer use is seven days or less. Hourly and daily rentals sit far below that line. The loss is nonpassive when you materially participate, and passive when you do not.
One test, more than 100 hours and not less than anyone else, compares you with your employees too. A guide who works the whole season will out-hour an owner who also has a day job.
The test that fits is the first one in the regulation: more than 500 hours in the year, with no comparison to anyone. Your spouse's hours count toward it. At 31 hours a week, a 20-week season comes to 620 hours.
A large year-one loss can also hit the excess business loss limit, which Rev. Proc. 2025-32 sets at $256,000, or $512,000 on a joint return, for 2026. A six-UTV shop stays well under it; a forty-UTV shop might not.
6 Six UTVs, one season
Take a married owner who buys six UTVs at $24,000 each and has them prepped and bookable in May 2026. The spouse has a W-2 job, the household stays in the 32% bracket, and the owner logs 620 hours. The season brings in $210,000 of rentals against $150,000 of guide wages, fuel, insurance, repairs, permits and marketing.
Cost, 6 x $24,000: $144,000
Operating profit before depreciation, $210,000 - $150,000: $60,000
100% bonus depreciation: ($144,000)
Schedule C loss, $60,000 - $144,000: ($84,000)
Tax saved if the loss is nonpassive, $84,000 x 32%: $26,880
Total tax effect of the bonus, $144,000 x 32%: $46,080
The $60,000 of profit is sheltered either way, because depreciation always offsets the shop's own income. Material participation decides what happens to the other $84,000. With it, the loss reduces tax on the spouse's wages this year, worth $26,880. Without it, the $84,000 is suspended until the shop has income or the owner sells the whole business, in a fully taxable sale, to an unrelated buyer.
These figures are federal income tax only and leave out state tax. If the shop is the owner's only self-employment, the loss also means no self-employment tax this year. It does not reduce the Social Security and Medicare tax withheld from the spouse's wages.
7 Selling the UTVs brings it back as ordinary income
When you rotate UTVs out after a few seasons, each one is section 1245 property, so any gain, to the extent of depreciation claimed, is ordinary income rather than capital gain.
Suppose the owner sells all six after three seasons for $11,000 each. With a zero basis, the whole $66,000 is ordinary income, about $21,120 at 32%. Over the three seasons the owner deducted $144,000 and gave back $66,000, a net $78,000 that matches what the UTVs lost in value, so bonus moves the deduction to year one without adding to it.
Trading UTVs in to a dealer does not avoid this. Like-kind exchange treatment has been limited to real property since 2018, so a trade-in is a sale of the old UTV.
8 The records that hold up
Section 274(d)(3) borrows its definition of listed property from section 280F, so we treat its proof rules as applying even when the leasing exception does. A rental shop already creates most of these records:
- Signed rental agreements. Each shows the date, UTV number, start and return time.
- Odometer readings out and in. Mileage is the measure the regulation uses for vehicles. Hour meters back them up.
- A log of every non-rental ride. Include guide scouting runs, repairs, and the owner's family weekend on UTV four. Personal use is never deductible.
- A weekly owner hours log. Cover bookings, safety briefings, maintenance and staff scheduling. Calendars and booking software timestamps work. Daily diaries are not required, but a round number reconstructed at year end is weak evidence.
The hobby loss rule in section 183 rarely reaches a shop with payroll and posted hours. It can reach one "rental" UTV that spends most weekends with the owner.
9 What to do before next season
- Get UTVs ready before December 31. Depreciation starts when a UTV is ready and available for rent. A snowmobile still crated on New Year's Eve is a 2027 deduction.
- Count your hours against 500, not 100. If you will not reach 500, decide before the season whether you or your spouse take on more of the work.
- Classify the UTVs as 7-year property. Keep a note of why, in case you later elect out of bonus or a state return needs its own schedule.
- Model the exit. Put the ordinary-income tax on the eventual sale into your cash plan the year you buy.
If you are adding UTVs this year, settle the hours question before the purchase, because it decides whether the deduction lands this April or waits for a sale. Our tax planning team models the bonus, your hours against the 500-hour line and the resale before you sign the dealer invoice.
General information for owner-operators, not tax advice for your situation. Thresholds change and state treatment varies; confirm current requirements for your own facts before acting.
Frequently asked
Questions, answered
Do snowmobiles and dirt bikes get the same treatment as UTVs?
Yes. Without four wheels they cannot be passenger automobiles, and as vehicles that carry people they are listed property. A shop renting them to the public all season qualifies for the leasing exception and full bonus on the same terms.
Can I take bonus depreciation on used UTVs?
Yes, if you never used the UTV before and bought it from someone who is not related to you. The 100% allowance is not limited to new equipment, so UTVs bought from a dealer or a retiring operator qualify.
What if I own one ATV and rent it out a few weekends a year?
There is still no dollar cap, but occasional rentals may not make you a leasing business. Then business use has to exceed half of how the ATV is used each year, or it moves to straight-line over 10 years with no bonus at all.
Does my spouse working the counter help with the hours test?
It does. The code adds a spouse's participation to the owner's when deciding material participation. Bookings, briefings and repairs by either of you go into one total, which helps a couple clear 500 hours.
Should I skip bonus in a year the loss would be passive?
Sometimes. Electing out applies to an entire property class for the year, so it would cover every 7-year asset you placed in service, not only the UTVs. A suspended loss is not wasted either. It carries forward, though selling to a relative or a company you control does not release it until the business passes to an unrelated owner.